
I’ve been looking at the Final stage Impact Assessment of the Highways (Financing) Bill published by the Lower Thames Crossing (LTC) team at the Department for Transport (DfT), which obviously tries to big up the legislation, but also flags a few pretty obvious risks.
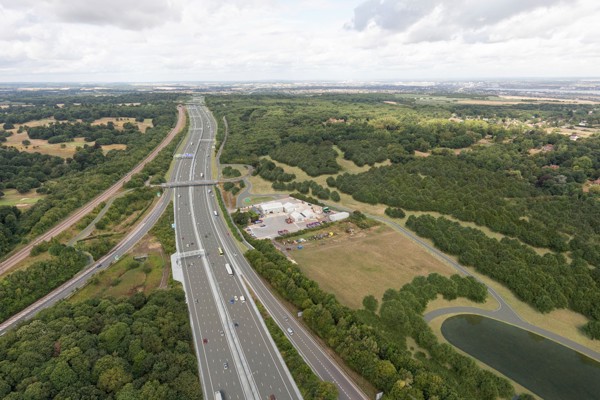
The LTC appears in the assessment as an example of how the mechanism of a Regulated Asset Base (RAB) model might get private money to build highways infrastructure in exchange for (toll) revenue and how some highways infrastructure might be handed over to a private entity.
The section on Risks, unintended consequences and assumptions sets out a few things that might go wrong, all quite likely and very good reasons not to deploy the model.
The section on Risk of higher road user charges sets out the basic model:
Under the RAB model, the regulated company (RegCo) is entitled to recover efficiently incurred capital and operational expenditures associated with the asset. In addition, the framework can allow for the RegCo to recover costs that would not typically arise under conventional public delivery, such as private financing costs, transaction and administration costs, and, depending on the licence and transaction, certain tax costs. These costs would be recovered by Road User Charges (RUCs) and associated revenue mechanisms.
So already there are additional costs, with the obvious consequence:
As a result, there is a risk that charges could be higher, or structured differently, than those that might be set under a public delivery model.
But its ok because:
Regulatory oversight can provide cost incentives, prevent excessive charges, and ensure that RUCs remain proportionate over the life of the scheme.
Note that the mitigation imports the word PR “ensure”, albeit attached to can, which makes it meaningless as a statement of certainty.
There is also the risk of Private sector inefficiencies:
(more…)


Leave a comment